About
Financial infrastructure, engineered by people who were there at the start.
Webovate is a senior, multidisciplinary consultancy working where financial technology, data and machine learning meet: the infrastructure that moves financial data, and the intelligence that makes sense of it. Established 2014. This is where the company came from, how it works and where it is going.
People
A senior, multidisciplinary team that scales to the work.
The people who scope the work are the people who do it. Depending on the engagement that is a single architect working with your team under contract, or a wider group of trusted design, engineering and data specialists we have worked with for years, and Webovate can bring in or substitute specialists from that group as an engagement requires. Never juniors billed as seniors.
-
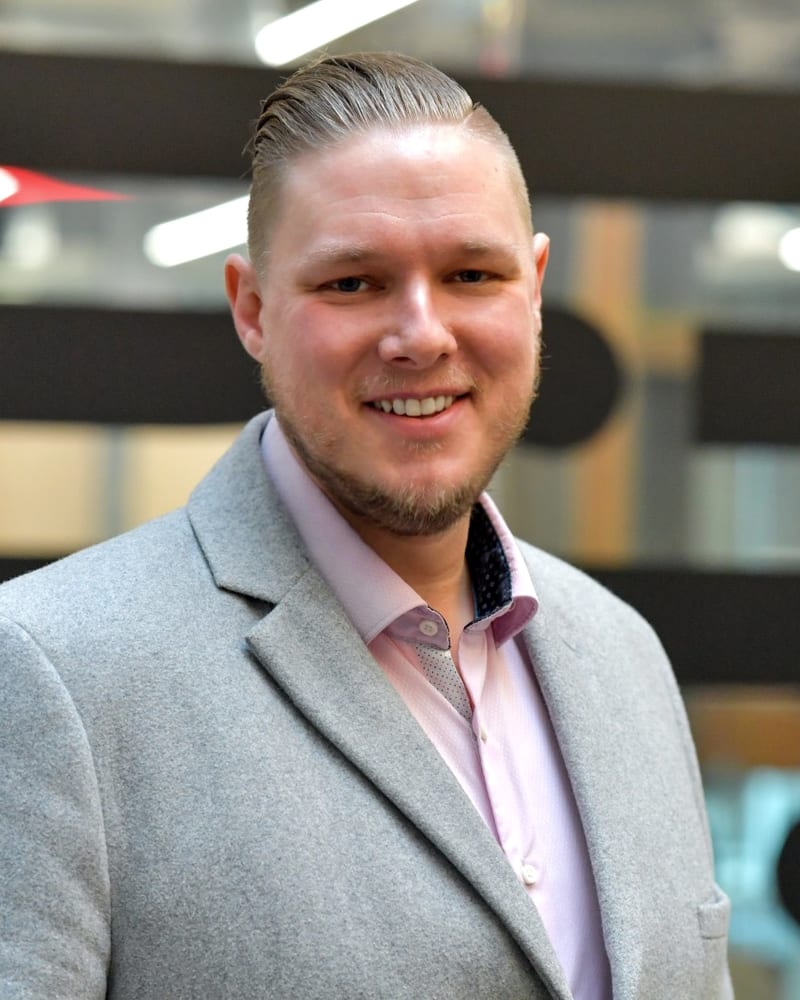
Glyn Jackson
Founder & Principal Architect
Glyn has been building financial software for more than twenty-five years: payment gateways in the early 2000s, cloud platforms for national brands through the 2010s, and Open Banking from within the implementation programme, where he worked on the Read/Write API architecture and then led the conformance product for the CMA9. He has been AperiData’s engineering partner since its foundation, building its platform and machine-learning categorisation engine, and leads Webovate’s work on applying AI to financial data. He still writes code most days.
LinkedIn -
P-04 · Edem Adjogatse portrait Edem Adjogatse
Design & Engineering Associate
Edem is a full-stack senior developer with a design focus and more than two decades of delivery on demanding client projects, from high-volume enterprise applications to the interfaces people use every day. He works with Webovate on product design and front-end engineering.
-
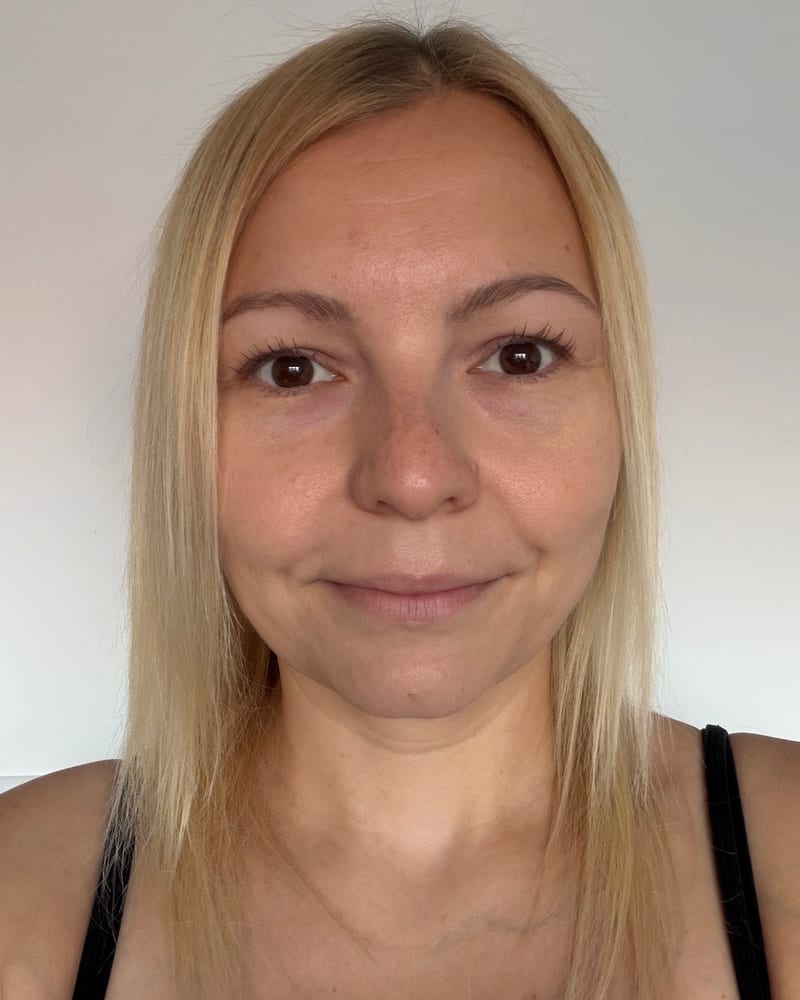
Melinda Kopa
Finance Coordinator
Melinda runs Webovate’s finance and accounts: bookkeeping, invoicing, client and supplier financial administration, and the company’s statutory accounts with our external accountants. She keeps the business running so the engineering can.
LinkedIn


Our story
Webovate was established in 2014 by Glyn Jackson, an engineer who had spent the previous fourteen years building payment gateways, digital-identity and financial platforms and cloud infrastructure: first as co-founder of a payments software company, then as lead architect for a digital agency's clients, including Samsung, HTC and the NHS.
When the Competition and Markets Authority's Order required the nine largest current-account providers to open customer data through a common API standard, Webovate built, in 2017 and within months of the standard's first release, one of the first Python connectors for the Read/Write APIs that existed at the time. Unknown to Webovate, that connector was already being used by the first team helping the Open Banking Implementation Entity get started, the body the banks had set up to deliver the standard. In December 2017, as the implementation programme restarted, the manager running that team invited Webovate to interview, and the company joined as a consultant: first in the support team, then quickly into the interim CTO's architecture team working on the Read/Write APIs. From 2018 to 2021 the company led the OBIE's conformance product for all nine mandated banks, from Barclays and HSBC to AIB and Bank of Ireland: workshops every two weeks in London, the tools that tested each implementation against the standard as it moved through the 3.1.x releases, and the reference applications and certification programme. Much of that tooling remains open source and in use today.
That experience ran in parallel with, and then led into, engineering for the companies building on the standard. Webovate was engaged by Ozone API to work with its engineers on the first model banks, and was later contracted by Ozone for a short full-time engagement, delivering the platform's first payment integrations, beginning with Stripe, and an international rollout. From 2021 the company became engineering partner and Open Banking specialist to AperiData, before it held any permissions: Webovate was engaged to build the entire platform from the first commit, through FCA authorisation as an account information service provider and on into a real-time credit bureau serving lenders across the United Kingdom, including the machine-learning categorisation engine at its heart. That work moved the company into the data the APIs produce: categorising transactions, modelling income and expenditure, and generating the affordability and risk signals lenders use to make decisions.
What began as a UK competition remedy became a template. The security profile the programme wrote went to the OpenID Foundation and became part of the Financial-grade API standard; the pattern it established, a directory, a common API standard and conformance testing, has since been adopted in one form or another from Brazil and Australia to the Gulf, and dozens of markets now run on it. The same ideas are being extended to Open Finance, to Smart Data across whole sectors of the economy, and to digital identity, where a person's consent and credentials travel with them. And a newer force is changing what can be done with the data once it moves: machine learning and AI can now read a financial life well enough to make the decisions taken about it fairer, faster and better informed.
Webovate did not build that movement, but it has worked inside it from the early days of the UK programme to production machine learning on consented data, in the UK, the Middle East and beyond. The company's focus now is where the movement is going: applying machine learning and AI to consented financial data to understand people and businesses properly, and helping the organisations that hold that data use it well. That is where we think the most useful engineering of the next decade will happen, and it is what we intend to keep pushing forward.
Timeline
12 years, 10 chapters.
-
2014
Founded
Webovate Ltd is founded on fourteen years of industry experience in payments, digital identity and platform engineering: from building early online payment gateways and PCI DSS-compliant systems to cloud platforms serving millions of users for Samsung, HTC and the NHS.
-
2015
Civic technology
Technical lead on CTZN with Gencia Media: a youth social-impact platform trialled by more than 120 organisations across Greater Manchester and recognised with awards including Digital Entrepreneur of the Year.
-
2016
Machine learning, early
Consultant architect to DigitalBridge, an award-winning computer-vision and machine-learning company building room visualisation tools for retailers. Webovate was contracted as the second engineer in the business and for a period the only one, designing the API and cloud architecture through a growth phase that included a John Lewis accelerator win and NVIDIA’s most innovative machine-learning start-up award, before the company grew an engineering team of its own.
-
2017
The beginning of UK Open Banking
In 2017, within months of the Read/Write standard’s first release, Webovate built one of the first Python connectors for it. Unknown to Webovate, it was already in use by the first team helping the Open Banking Implementation Entity get started, the body set up by the banks to deliver the standard. In December 2017 the manager running that team invited Webovate to interview, and the company joined as a consultant: first in support, then quickly into the architecture team working on the Read/Write APIs, and from there to leading conformance tooling for the CMA9.
-
2018
Conformance for the CMA9
Webovate leads the OBIE conformance product for the CMA9: ownership and delivery of the tools that tested all nine mandated banks against the standard as it moved through the 3.1.x releases, with workshops every two weeks in London with Barclays, HSBC, Lloyds Banking Group, NatWest, Santander, Nationwide, Danske Bank, AIB and Bank of Ireland, plus the reference applications and certification programme.
-
2020
Payments and platforms
After the OBIE work, Webovate is contracted by Ozone API for a short full-time engagement, delivering the platform’s first payment integrations, beginning with Stripe, and the architecture for an international open banking rollout in the Middle East.
-
2021
A credit bureau from the first commit
Webovate is engaged as AperiData’s engineering partner and Open Banking specialist from the company’s foundation, before it held any permissions: the platform that supported FCA authorisation as an account information service provider and, as the business grew into a real-time credit bureau, everything underneath it: Open Banking connectivity, the categorisation engine, income and expenditure modelling and affordability analysis.
-
2024
Financial intelligence at scale
The categorisation and affordability work matures into production decisioning across the lending lifecycle. PayPoint makes a strategic investment in AperiData.
-
2026
Intelligent, connected finance
PayPoint completes its acquisition of AperiData, and the platform and categorisation engine Webovate was engaged to build now serve a listed payments group. Commercial variable recurring payments go live in the UK and the FCA sets out its Open Finance roadmap. Working with AperiData, Webovate begins applying language models to categorised financial data.
-
Today
What we are building now
Continuing as AperiData’s engineering partner, now within the PayPoint Group, on categorisation and financial-health intelligence; Open Finance and Smart Data readiness for clients; and the Lab: financial health from consented data, Open Banking for accountancy, and machine learning for rider safety.
How we work
Three ways to engage us.
-
Architecture and delivery
We scope, design and build, with the same senior people throughout. Fixed-scope or time-based, on site or remote.
-
Contracted technical leadership
CTO-level engineering leadership delivered under contract for a defined period, from platform build-out to acquisition readiness.
-
Advisory and due diligence
Standards, security-profile and architecture advice, and technical due diligence on Open Banking and financial-data businesses for investors and acquirers.
Direction
From Open Banking to intelligent, connected finance.
Open Banking started as a competition remedy and became the template for consented data sharing worldwide: Open Finance, Smart Data, digital identity. The next step is intelligence. We apply machine learning and AI to that data to understand people and businesses properly, and we think that is the most useful thing a financial-technology engineer can do right now.
-
Open Finance and Smart Data
The Data (Use and Access) Act 2025 created the framework for smart data schemes beyond banking, and the FCA has set out open finance as a priority. The patterns are familiar to anyone who implemented Open Banking: directories, consent, security profiles, conformance. We have done that work once already.
-
Machine learning on Open Banking data
Consented transaction data describes a household or a business far more accurately than a bureau score, but only once a machine can read it. Categorisation, income and expenditure modelling and affordability analysis are where we have spent the last five years, and where we see the most value for lenders, advisers and the people they serve.
-
Commercial VRP and payments
Commercial variable recurring payments went live in 2026. Recurring, consented account-to-account payments change the economics of collections and subscriptions, and they need careful integration with consent and risk controls.
-
AI that understands financial lives
Language models and agents can now reason over a categorised financial history, explain it, and act on it with consent. We are building towards that carefully: analysis and evaluation first, decision support second, always with the identity, consent and audit controls that regulated use demands.
Lab
Engineering on our own account.
Alongside client work we run research projects that stretch the same skills: machine learning on messy real-world data, consented financial data, and systems where getting it wrong has consequences. They keep us sharp and they occasionally become products.
-
Active, in production with clients
Financial health from consented data
-
Prototype
Open Banking for accountancy workflows
-
Research
Machine learning for rider safety
Talk to us about your project.
Tell us what your project is and where it is stuck. We will always try to help.
hello [at] webovate [dot] co [dot] uk How to get in touch